


Dear Readers,
October brought something we had not seen much of earlier this year: buyers gaining some negotiating room, even as certain base oils remained difficult to secure.
For North America, the change was most noticeable in heavier grades. Refiners had more material available, export opportunities were becoming less attractive, and buyers were increasingly reluctant to carry expensive inventory into the end of the year. This created an unusual situation where some suppliers were becoming more competitive while others were still protecting prices on grades that remained difficult to replace.
Diesel economics and the Middle East continued to influence the picture, but October was increasingly shaped by what was happening inside the market itself. Buyers were managing cash flow, suppliers were reconsidering inventories, and blenders were becoming more selective about what they purchased and when.
The result was a month where the direction of pricing depended heavily on the grade, the supplier, and the buyer’s flexibility.
Quick Highlights – Group I, Group II, and Group III
Group I became increasingly competitive in October, particularly in North America.
U.S. refiners entered the month with healthier inventories following a relatively quiet hurricane season. Demand was softer than many had anticipated, and the normal pressure to manage inventories before year end encouraged sellers to become more aggressive on certain grades.
SN500 and other heavier grades felt that pressure most clearly. Some refiners were willing to discuss discounts or package multiple grades together to encourage buyers to take additional material. Light and medium viscosity grades were also becoming easier to secure, although availability varied by supplier.
Bright stock remained somewhat different. Supply continued to improve, but the grade still carried more sensitivity because replacement options are limited for certain industrial and heavy duty formulations. The ongoing turnaround at PBF’s Paulsboro refinery also restricted some export availability, with additional volumes not expected until at least December.
What stood out in October was that improved availability did not necessarily translate into stronger demand. Blenders were watching their own inventories closely, and some preferred to purchase only what they needed rather than commit to additional barrels at elevated prices.
Group II showed an even greater difference between grades.
N600 was increasingly available, while N220 continued to improve as the month progressed. That gave buyers more flexibility than they had enjoyed during the summer. N100, however, remained comparatively difficult to secure.
Part of the N100 issue is tied to changes in refinery yields, but another important factor is the continued shortage of Group III 4cSt. Where formulations permit, some blenders have been using lighter Group II and Group II+ material to reduce their dependence on Group III. This has supported N100 demand even as heavier Group II grades have become more plentiful.
October’s producer postings reinforced how differently suppliers were approaching the market. Motiva implemented increases on several Group II, Group II+ and Group III grades at the beginning of the month, while ExxonMobil moved its EHC 45 posting higher in mid October. At the same time, more competitive offers were appearing for heavier grades.
To us, this was one of the more interesting developments of the month. Published prices were not always moving in the same direction as the prices being discussed for available material. Producers continued to protect the value of grades with limited replacement options, while becoming more flexible where inventories were growing.
Diesel remained an important part of that decision making.
Base oil production was still economically attractive for U.S. refiners, but the advantage over diesel was narrowing as base oil values softened. If that trend continues, refiners may eventually have greater incentive to direct suitable feedstocks toward transportation fuels rather than additional base oil production.
That possibility matters because greater availability today does not guarantee the same supply picture several months from now. Refiners can adjust their production priorities, and changes in crude slates can affect the yields of individual base oil grades even when refinery operating rates remain strong.
Group III remained the most difficult part of the market, although October finally brought some potential relief into view.
Cargoes originating in the Middle East were expected to reach the U.S. Gulf Coast toward the end of the month. Their arrival would be welcome, but much of that material was already needed to satisfy existing contractual commitments and outstanding orders. We do not believe these shipments alone will restore normal availability.
Approved 4cSt continued to carry the greatest concern. Demand remained strong, and production difficulties associated with changing crude inputs further restricted supply. By comparison, 6cSt and 8cSt were somewhat more available, with limited opportunities for buyers to secure material outside their regular commitments.
This distinction is important. The arrival of additional Group III barrels does not necessarily solve a shortage if the incoming grades or approvals are not what a blender requires.
Some Indian and Chinese Group III material continued to attract attention because of its more competitive pricing. However, differences in viscosity index, specifications and OEM approvals limited its usefulness in many North American formulations. Buyers with greater flexibility had more options, while those tied to approved products remained dependent on a smaller supplier base.
October also brought greater attention to 2027 supply agreements. Some blenders were looking to increase contracted volumes to protect against further disruptions, while certain refiners were considering higher premiums or greater flexibility in monthly pricing. In our view, securing dependable supply is becoming just as important as negotiating the initial price.
Naphthenics followed a different path.
Light grades remained the stronger part of the market, with pale oil 60 benefiting from continued specialty oil demand and pale oil 100 supported by metalworking and other industrial applications.
Heavier naphthenic grades faced a more difficult environment. Demand from tire and rubber applications remained soft, while improving availability and lower offers for heavy paraffinic base oils reduced some of the incentive to substitute into naphthenics.
That is an important change from earlier months. When paraffinic availability was limited and prices were rising, naphthenics offered an attractive alternative in certain applications. With heavier paraffinic grades becoming more competitive, some of that advantage has narrowed.
Latin America continued to influence how aggressively U.S. refiners priced their available barrels.
Asian suppliers remained competitive, but higher freight costs and longer delivery times were beginning to complicate purchasing decisions. For buyers concerned that prices might decline before an imported cargo arrived, waiting or securing material closer to home became more attractive.
This created an opportunity for U.S. Gulf Coast sellers, particularly as they looked to reduce inventories before the end of the year. More competitive offers began appearing in Mexico and along parts of South America’s west coast.
Brazil also saw a noteworthy change. Although lighter Group I grades experienced some tightness during October, a major domestic refiner announced reductions to its November Group I postings. This reflected growing concern over lower replacement costs and continued competition from U.S. and Asian suppliers. The important development was no longer the earlier refinery maintenance, but how suppliers were responding to the changing price environment.
Mexico remained under pressure from softer finished lubricant demand, currency concerns, and competitive imported material. Additional U.S. offers provided buyers with more options, although purchasing remained cautious.
For North American refiners, export opportunities were still present, but simply having barrels available was no longer enough. Price, delivery timing, and the buyer’s ability to finance inventory were becoming increasingly important.
October ultimately showed how differently individual base oil grades can behave within the same market.
Buyers of heavier Group I and Group II material had more negotiating room, while those requiring N100 or approved Group III 4cSt continued to face limited alternatives. Refiners were managing inventories and watching diesel economics, and blenders were increasingly focused on purchasing only what they could reasonably use.
Closing Remarks:
As we move toward the end of the year, the question is no longer simply how much base oil is available. It is whether the right grades can be secured at a cost that makes sense for the finished lubricant being produced.
RECENT HEADLINES
U.S. REFINERIES
Chevron and Exxon hit all-time highs as refining profits soar in reaction to Iran and Ukraine wars
Chevron and ExxonMobil on Friday reported profits that soared in the third quarter, as their U.S. refineries ramped up production to full capacity to take advantage of high diesel fuel prices.
Chevron shares are up nearly 2% while Exxon is more than 1% higher. Both touched all-time highs Friday.
The world is facing a fuel crisis as Ukraine, Iran and Houthi militants attack refineries in Russia and the Middle East, reducing global capacity by millions of barrels per day. Importers have increasingly turned to U.S. Gulf Coast refineries for diesel supplies as a consequence.
ExxonMobil’s profits doubled to $15.4 billion, or $3.72 a share, compared to $7.5 billion, or $1.76 a share, in the same period in 2025. When adjusted for one-time items, it posted earnings of $4.23 a share, soundly beating Wall Street’s expectations. Continue Reading Here
Phillips 66 posts record quarterly profit on refining strength
NEW YORK, Oct 28 (Reuters) – Phillips 66 (PSX.N), on Wednesday reported a record quarterly profit, topping Wall Street estimates, powered by higher refining margins on fuel supply disruptions due to the wars in Iran and Ukraine.
US fuelmakers benefited from historically wide refining margins as global fuel supplies have tightened and inventories have depleted on a war-related supply crunch in both the Middle East and Russia. Prices for diesel, which underpins everything from manufacturing to agriculture, have hit record highs, creating pain for consumers and US President Donald Trump’s Republican party, but a boon for refiners. Continue Reading Here
NON U.S. REFINERIES
Yemen’s Houthi Rebels Strike Saudi Aramco’s Ras Tanura Oil Terminal
Yemen’s Houthi rebels claim to have hit the Saudi energy complex at Ras Tanura, a gigantic refinery and loading terminal that handles an outsize share of the world’s oil supply. It is the latest strike deep into the heart of Saudi territory, and it targeted one of the most valuable locations in the kingdom’s energy-centric economy.
“The Houthis have turned Saudi infrastructure into target practice with remarkably little resistance. From airports to critical energy infrastructure, virtually nothing appears beyond their reach,” Obsidian Risk Advisors principal Brett Erickson told Al-Monitor. “That is an extraordinarily dangerous position for the global energy market to be in.” Continue Reading Here
Infineum’s Potential Sale: What History Reveals and What Buyers Would Weigh
The possibility of a sale of Infineum, the lubricant and fuel additives joint venture owned equally by Shell and ExxonMobil, is drawing attention following reports that its owners are exploring a transaction valued at approximately $8 billion.
On October 22, Reuters, citing the Financial Times (FT), reported that Bank of America had been retained to run a potential sale process. The report indicated that private-equity firms could be interested but cautioned that discussions remain in their early stages and may not result in a transaction. No prospective buyers were identified.
For the lubricant industry, a potential sale would be significant. Infineum is one of the world’s major suppliers of lubricant and fuel additives, competing with Lubrizol, Afton Chemical and Chevron Oronite. Its technologies are used in passenger car and heavy-duty engine oils, driveline fluids, industrial lubricants and other applications. Continue Reading Here
Six oil tankers carrying 268,000 tonnes of Russian diesel sail towards US
Six oil tankers carrying an estimated 268,000 tonnes of Russian diesel are now sailing towards the US, though it is uncertain if the vessels will be able to unload amid a political row about the legality of the shipments.
The transport, tracked by the pressure group Greenpeace, is the first phase of a contentious supply deal negotiated between presidents Donald Trump and Vladimir Putin earlier this month, reversing years of sanctions on Russia oil.
Previous reports had counted three tankers that had departed Russian oil terminals in the Baltic Sea, but using a range of sources, including shipping tracking websites, Greenpeace believes its monitoring exercise is the most complete yet. Continue Reading Here
THE CRUDE SIDE
US crude and distillate inventories fall, gasoline stocks rise, EIA says
DENVER, Oct 28 (Reuters) – US crude and distillate inventories fell due to higher demand, while gasoline stockpiles rose last week, the Energy Information Administration said on Wednesday.
Crude inventories fell by 1.9 million barrels to 410.6 million barrels in the week ended October 23, the EIA said, compared with analysts’ expectations in a Reuters poll for a 15,000-barrel rise. Continue Reading Here
Chinese oil refiners turn to African and Brazilian oil as falling freight rates open new buying opportunities beyond Russia
Some Chinese refiners have purchased West African and Brazilian crude for December delivery at premiums of up to $20 per barrel above ICE Brent, according to Bloomberg.
The shift comes after tanker rates surged following the escalation of the Iran war, making long-distance crude shipments significantly more expensive. Shipping a cargo of oil from the U.S. Gulf Coast to China reportedly cost as much as $80 million earlier this month, roughly ten times the historical average tanker rates.
Although freight costs have eased, shipping a supertanker from the United States to Asia still cost about $60 million last week, discouraging Asian refiners from placing substantial orders for U.S. crude for November delivery. Continue Reading Here
Surprising Fun Facts About the Oil Industry
- Shell oil tankers were converted into aircraft carriers during World War II. Nine Shell oil tankers were converted into merchant aircraft carriers between 1943 and 1944. They were fitted with flight decks so aircraft could help protect Allied convoys from German submarines. The vessels continued carrying commercial cargo while serving this military role.
- The largest oil tanker ever built was longer than four football fields. The Seawise Giant, completed in 1979, measured 1,504 feet long and had a deadweight capacity of 564,763 metric tons. It was so enormous that its fully loaded draft prevented it from passing through the Suez and Panama Canals. It was scrapped in 2010.
- The United States stores emergency crude oil inside giant underground salt formations. The U.S. Strategic Petroleum Reserve uses underground caverns carved into salt domes in Texas and Louisiana. When oil is withdrawn, water can be pumped into the bottom of a cavern, physically pushing the crude upward and out through the well.
- Some crude oil tankers clean their tanks using crude oil itself. A process called crude oil washing uses the ship’s own crude cargo to remove oil deposits from tank walls. The crude acts as a solvent, reducing accumulated residue and the need for water washing. The practice is regulated internationally.
- The Soviet Union once used a nuclear bomb to extinguish a burning natural gas well. In 1966, Soviet engineers detonated a 30-kiloton nuclear device approximately 5,000 feet underground in Uzbekistan to stop a natural gas well fire that had burned uncontrollably for nearly three years. The explosion compressed the surrounding rock, sealing the well and extinguishing the fire within 23 seconds.
- Saudi Arabia’s oil industry was transformed by its seventh exploration well. After six earlier wells failed to establish sustained commercial production, Standard Oil of California struck commercially significant oil at Dammam Well No. 7 in March 1938. The well initially produced 1,585 barrels per day and ultimately yielded more than 32 million barrels before being shut down in 1982.
- A massive American oil pipeline was constructed specifically because German submarines were sinking tankers. During World War II, the United States built the 24-inch-diameter Big Inch pipeline to transport crude from Texas toward the Northeast. German U-boats had disrupted coastal tanker movements, making an inland petroleum transportation system strategically important.
- More than 600 Kuwaiti oil wells were burning simultaneously during the Gulf War. Iraqi forces deliberately damaged and ignited hundreds of oil wells in 1991. According to U.S. government records, 610 wells were burning following the liberation of Kuwait. International firefighting teams extinguished the last fire on November 6, 1991.
- One California oil well released approximately 9 million barrels of crude before it could be controlled. In March 1910, the Lakeview Gusher in Kern County, California, erupted and began releasing enormous quantities of crude oil. At its peak, the uncontrolled well flowed approximately 100,000 barrels per day. It continued for roughly 18 months, ultimately releasing an estimated 9 million barrels, making it one of the largest oil well blowouts ever recorded.
- Much of the world’s helium supply actually comes from natural gas production. Helium occurs naturally in certain underground gas reservoirs and can be separated during natural gas processing. Qatar, for example, produces commercial helium from its North Field gas resources. This helium is used in MRI machines, semiconductor manufacturing, and other specialized applications.
SUGGESTED READING
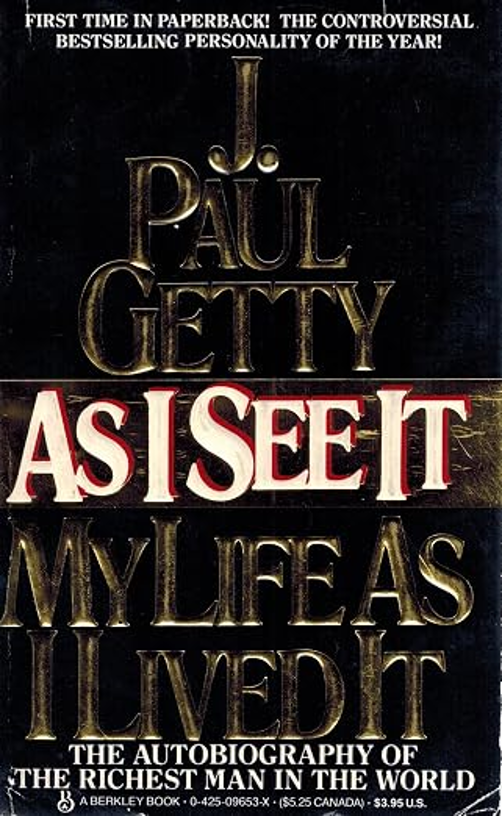
As I See It offers a fascinating look into the life of J. Paul Getty, one of the wealthiest and most influential oilmen in history. From building a global petroleum empire to navigating high-stakes business deals, Getty shares his personal experiences, successes, and lessons learned along the way. Filled with stories of ambition, wealth, and larger-than-life personalities, it is an entertaining read for anyone who appreciates the entrepreneurial spirit and colorful history of the oil industry.
WE’VE COME A LONG WAY!
Thank you for joining us in this edition of the Beyond the Barrel Newsletter. Feel free to reach out to the Signal Fluid Solutions team for any inquiries or discussions.