


Dear Readers,
October brought a different kind of pressure to the petroleum market.
By this point in the year, the industry is usually settling into a familiar rhythm. Summer demand begins giving way to winter planning, refiners start thinking about maintenance schedules, and buyers begin positioning themselves for the colder months ahead.
But this October, the usual seasonal transition was anything but ordinary.
The challenges were no longer confined to keeping supply moving. They were increasingly about the economics behind those movements, the decisions refiners were willing to make, and the growing differences between regional markets.
Some of those changes were obvious. Others were quietly developing beneath the surface.
And as we move toward the final months of the year, those differences may become increasingly important.
Crude Oil Market Overview
October brought renewed pressure to U.S. crude inventories, even as refinery operations remained relatively strong for this time of year.
Commercial crude stocks began the month near 424 million barrels before declining to approximately 410.6 million barrels by the week ending October 23. That moved inventories from slightly above their five-year seasonal average to roughly 4 percent below it.
What makes this interesting is the timing.
October traditionally brings increased refinery maintenance as operators prepare for winter. Yet refinery utilization remained above 92 percent through the period, with crude inputs holding around 16.5 to 16.6 million barrels per day.
Those are still substantial operating rates for a period when maintenance would normally receive greater attention.
The economics help explain why.
Strong diesel margins and continued export opportunities give refiners a financial incentive to maintain production wherever practical. Taking equipment offline carries a cost, especially when international markets continue competing for refined products. While some maintenance cannot be postponed, there is little reason for operators to surrender profitable production days unnecessarily.
Meanwhile, crude imports fluctuated throughout October, ranging from approximately 6.0 to 6.8 million barrels per day in the weeks covered. Those movements were not sufficient to prevent the broader decline in domestic inventories.
That creates an interesting situation heading into November.
Refiners are navigating the usual seasonal maintenance decisions, but the economics favor keeping capacity available. At the same time, crude inventories are no longer holding the relatively comfortable position seen during September.
We do not necessarily see this as evidence of an outright crude shortage. However, continued inventory draws could make the market more sensitive to interruptions in imports, refinery schedules, or international cargo movements.
The next several weeks will be important in determining whether the October decline was temporary or the beginning of a more sustained adjustment in U.S. crude availability.
Bunker Fuel Insights
October brought another change in the global bunker market, particularly in the relationship between low sulfur and high sulfur marine fuels.
Marine fuel pricing continued strengthening as geopolitical uncertainty, higher crude values, and regional supply constraints worked their way through international bunkering hubs.
Singapore was particularly interesting.
By late October, VLSFO pricing had moved to approximately $1,000 per metric ton, while HSFO approached $910 per metric ton. That left a much narrower price difference between the two products than buyers have traditionally been accustomed to seeing.
For operators using scrubber-equipped vessels, that matters.
The financial advantage of burning HSFO depends partly on the discount available against compliant low sulfur fuel. When that difference narrows, the economics behind scrubber investments and fuel purchasing begin to change.
Singapore’s continued strength in marine fuel sales also contributed to the picture. Conventional and biofuel bunker volumes reached nearly 42 million metric tons during the first nine months of the year, with HSFO sales continuing to expand.
Houston presented a different situation.
By the final week of October, VLSFO was trading around $840 per metric ton, while HSFO remained closer to $620. That represented a substantially wider discount than Singapore, highlighting the growing differences between the Atlantic and Asian bunker markets.
Fujairah remained another area worth watching.
Despite some recovery from the unusually weak activity earlier this year, bunker sales continued running well below historical levels. Ongoing disruption affecting Middle Eastern shipping routes has changed where vessels choose to refuel, leaving some traditional hubs struggling to regain lost business.
For marine fuel buyers, the implications extend beyond the price of an individual bunker stem.
Fuel selection, vessel routing, and the economics of scrubber operations are increasingly influenced by the region in which a vessel is trading.
A ship operating primarily in Asia may face a very different fuel cost calculation than one trading between the United States and Europe.
That geographic difference was one of October’s more significant bunker developments.
Fuel Oil Sector Highlights
Fuel oil took a somewhat different direction from crude during October.
U.S. residual fuel oil inventories remained relatively steady, moving from approximately 23.9 million barrels at the beginning of the month to 23.4 million barrels by October 23.
More importantly, national inventories remained above the comparable period last year, suggesting that the domestic residual fuel oil market was not experiencing the same inventory pressure seen in crude.
However, regional movements told a more interesting story.
The Gulf Coast, which accounts for the largest share of U.S. residual fuel oil inventories, experienced a gradual decline. Stocks moved from approximately 14.1 million barrels early in October to 13.1 million barrels by the final week covered.
The East Coast remained comparatively steady, while West Coast inventories improved modestly.
Those differences matter because residual fuel oil availability is heavily influenced by where it is produced, stored, and ultimately consumed.
The Gulf Coast remains the most important domestic center for residual fuel oil production, blending, and exports. Changes in the region can influence how much material is available to international buyers, particularly those sourcing heavy fuel components from the United States.
Refinery economics also continue to influence the supply picture.
With refiners concentrating on profitable transportation fuels, residual streams are increasingly subject to decisions about further processing, blending, or export. Complex refineries can convert heavier material into lighter products rather than leaving it available for the conventional fuel oil pool.
That distinction becomes important when comparing domestic inventories with international fuel oil pricing.
While U.S. residual stocks were relatively healthy compared with last year, parts of the Asian marine fuel market continued experiencing pressure on high sulfur availability. The difference illustrates how domestic supply conditions do not always translate directly into international fuel oil pricing.
For the coming months, we will be watching Gulf Coast residual inventories and whether international demand begins drawing more heavily on available U.S. material.
INTERESTING FACTS
- Shell oil tankers were converted into aircraft carriers during World War II. Nine Shell oil tankers were converted into merchant aircraft carriers between 1943 and 1944. They were fitted with flight decks so aircraft could help protect Allied convoys from German submarines. The vessels continued carrying commercial cargo while serving this military role.
- The largest oil tanker ever built was longer than four football fields. The Seawise Giant, completed in 1979, measured 1,504 feet long and had a deadweight capacity of 564,763 metric tons. It was so enormous that its fully loaded draft prevented it from passing through the Suez and Panama Canals. It was scrapped in 2010.
- The United States stores emergency crude oil inside giant underground salt formations. The U.S. Strategic Petroleum Reserve uses underground caverns carved into salt domes in Texas and Louisiana. When oil is withdrawn, water can be pumped into the bottom of a cavern, physically pushing the crude upward and out through the well.
- Some crude oil tankers clean their tanks using crude oil itself. A process called crude oil washing uses the ship’s own crude cargo to remove oil deposits from tank walls. The crude acts as a solvent, reducing accumulated residue and the need for water washing. The practice is regulated internationally.
- The Soviet Union once used a nuclear bomb to extinguish a burning natural gas well. In 1966, Soviet engineers detonated a 30-kiloton nuclear device approximately 5,000 feet underground in Uzbekistan to stop a natural gas well fire that had burned uncontrollably for nearly three years. The explosion compressed the surrounding rock, sealing the well and extinguishing the fire within 23 seconds.
- Saudi Arabia’s oil industry was transformed by its seventh exploration well. After six earlier wells failed to establish sustained commercial production, Standard Oil of California struck commercially significant oil at Dammam Well No. 7 in March 1938. The well initially produced 1,585 barrels per day and ultimately yielded more than 32 million barrels before being shut down in 1982.
- A massive American oil pipeline was constructed specifically because German submarines were sinking tankers. During World War II, the United States built the 24-inch-diameter Big Inch pipeline to transport crude from Texas toward the Northeast. German U-boats had disrupted coastal tanker movements, making an inland petroleum transportation system strategically important.
- More than 600 Kuwaiti oil wells were burning simultaneously during the Gulf War. Iraqi forces deliberately damaged and ignited hundreds of oil wells in 1991. According to U.S. government records, 610 wells were burning following the liberation of Kuwait. International firefighting teams extinguished the last fire on November 6, 1991.
- One California oil well released approximately 9 million barrels of crude before it could be controlled. In March 1910, the Lakeview Gusher in Kern County, California, erupted and began releasing enormous quantities of crude oil. At its peak, the uncontrolled well flowed approximately 100,000 barrels per day. It continued for roughly 18 months, ultimately releasing an estimated 9 million barrels, making it one of the largest oil well blowouts ever recorded.
- Much of the world’s helium supply actually comes from natural gas production. Helium occurs naturally in certain underground gas reservoirs and can be separated during natural gas processing. Qatar, for example, produces commercial helium from its North Field gas resources. This helium is used in MRI machines, semiconductor manufacturing, and other specialized applications.
SUGGESTED READING
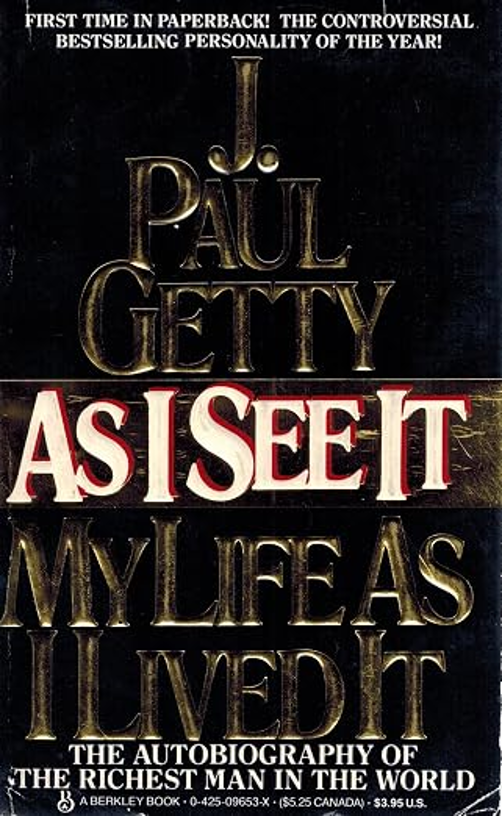
As I See It offers a fascinating look into the life of J. Paul Getty, one of the wealthiest and most influential oilmen in history. From building a global petroleum empire to navigating high-stakes business deals, Getty shares his personal experiences, successes, and lessons learned along the way. Filled with stories of ambition, wealth, and larger-than-life personalities, it is an entertaining read for anyone who appreciates the entrepreneurial spirit and colorful history of the oil industry.
FINAL THOUGHTS
October reinforced something we have been watching throughout the year: the economics of producing and moving petroleum are becoming just as important as the physical availability of the barrels themselves.
As we approach November, the question is whether refinery operations can continue at favorable rates without allowing inventories to deteriorate further. At the same time, the narrowing discount between high sulfur and low sulfur marine fuels in Asia introduces another variable for bunker buyers.
We believe the coming months will require closer attention to refinery operating decisions, regional product differences, and the direction of international cargo movements.
The market has become increasingly interconnected, but the opportunities and risks remain very different depending on which part of the barrel you are watching.
The Signal Fluid Solutions team would like to take this time to thank you for your business and thank you for allowing us to be an important part of you supply team.
Tyler Jordan – Oil Trading Manager – 909.203.0237