


Dear Readers,
September was a month where the base oil market felt steadier, but not necessarily easier.
For North American buyers, the panic of earlier summer was not as obvious. Contract supply was better than it had been in May, June, or even parts of August. Some grades became easier to talk about, and a few uncommitted barrels began to surface as refiners looked ahead to the end of hurricane season and the normal inventory decisions that come with the fourth quarter.
But that does not mean the market turned loose.
Buyers were still watching inventories and cash flow. Refiners were still watching diesel margins, crude volatility, and geopolitical risk. Blenders were still trying to pass through higher costs without losing demand. Everyone wanted relief, but nobody seemed ready to fully trust it yet.
The global story still mattered, especially with continued pressure around the Middle East, the Red Sea, and refinery disruptions abroad. But the most important question for North America was more practical: can supply improve without the market losing discipline, and can refiners keep producing base oils when diesel remains so attractive?
September was not a reset. It was a step away from shortage, but not a clean move into comfort.
Quick Highlights – Group I, Group II, and Group III
The North American market started to show more flexibility in September.
Earlier in the summer, the conversation was mostly about what could not be found. By September, that started to change. Some buyers were seeing better availability within contracts. Some refiners and sellers were more willing to discuss extra volume. The improvement was real, but it was uneven.
Group I showed the clearest signs of improvement.
Light and mid-viscosity grades became more available, and heavy-grade supply was healthier than it had been earlier in the year. That gave buyers a little more room to breathe. Refiners were still careful, but the tone was not as tight as it had been through the summer.
Bright stock remained the exception. It was improving, but it was still the grade buyers had to watch closely. Bright stock does not have the same easy replacement options as some lighter grades, and any disruption still matters quickly for heavy-duty, industrial, and specialized formulations.
The PBF turnaround added another reason for buyers to stay alert. Even with overall Group I availability improving, scheduled refinery work can still limit flexibility. That is the September story in one place: more supply in some areas, but not enough comfort to ignore risk.
Group II was more complicated.
Contract customers were generally in a better position, and the market had clearly adjusted from the tightest parts of the summer. N600 began to look longer, and N100 availability improved. But N220 remained tight, even if it was moving in a better direction. That made Group II feel less like a shortage across the board and more like a grade-by-grade market.
Lower-priced Asian supply also became more important, but it did not completely reset the North American market. Freight, timing, approvals, formulation needs, and reliability all mattered. A cheaper barrel somewhere else only helps if it arrives on time and fits the application.
For U.S. refiners, the bigger issue remained diesel.
Diesel margins stayed strong, and global fuel inventories remained tight. That kept a floor under base oil economics, even as some grades became more available. If diesel production looks more attractive than base oil production, refiners have every reason to stay disciplined. That is why we still do not see a straight line down in North American base oil values.
The September posted-price activity also showed the market was not moving in only one direction. Chevron moved Group II prices higher late in the month, and Petro-Canada moved Group III higher. That matters because it came at a time when some Group I and Group II grades were showing better availability. Producers were not simply chasing volume. They were still protecting value, especially where structural supply risks and future replacement costs remain uncertain.
In our view, September did not change the longer-term North American story. There is more breathing room, but not a clear path to oversupply. Even if Middle East logistics improve, refiners still need stable crude and feedstock flows, approved Group III supply still needs to normalize, and North America still has to absorb structural changes in Canadian base oil supply. Any relief is more likely to happen in stages than all at once.
Group III remained the most fragile part of the market.
The tone improved slightly late in the month because there was discussion of Middle East-origin material moving toward the U.S. by late October. That helped ease some concern, but it did not solve the problem. Approved Group III remained tight, and 4cSt stayed the most sensitive grade because of how widely it is used in formulations.
For buyers who require approved material, September was still difficult. Some blenders had adjusted where they could, but flexibility remained limited. Group II, Group II+, PAO, re-refined material, Indian Group III, and Chinese Group III can help in certain applications, but they are not automatic replacements. Approval requirements and customer specifications still decide what can actually be used.
That is why Group III continues to feel different from the rest of the market. It is not just a question of price. It is a question of whether the right material exists for the right formulation. If it does not, a finished lubricant cannot always be made the same way.
Naphthenics were steadier, but September added a little more movement than prior months.
Light grades stayed the tighter side of the naphthenic market, supported by Unique Industrial and metalworking demand applications. Mid and heavy grades were more balanced. This continued the same general pattern we saw in August, but September had a clearer pricing signal, with San Joaquin announcing an increase on select specialty oils during the month.
The bigger picture is still the relationship between naphthenics and paraffinic base oils. Naphthenics have not moved the same way as paraffinics, which keeps them attractive where formulations allow. But that does not mean producers want to overextend. Substitution demand can help sellers, but it can also pull supply away from regular customers. That keeps producers careful.
Latin America told a cleaner story in September: buyers with options pushed back on higher-priced U.S. barrels.
Contract exports still moved, but discretionary demand became more selective as South Korean and Indian barrels became more visible. Brazil fits into that story because the maintenance itself is no longer the news. The important point now is the result. With local Group I availability in better shape, Brazilian buyers had more leverage, and imported offers faced more pressure.
Mexico remained cautious, with high costs and currency pressure weighing on demand. For North American refiners, the message was simple: export outlets were still there, but price resistance was stronger, and surplus barrels had to compete harder.
The main September takeaway is that the market gave buyers more room, but not full relief.
Group I improved, though bright stock still needed attention. Group II was better supplied, but N220 remained tight and diesel kept a floor under values. Group III stayed the biggest risk, especially approved 4cSt material. Naphthenics stayed steadier, with light grades still supported and substitution interest still present.
Closing Remarks:
September was the first month where parts of the market felt more workable. Inventories improved, but risk did not disappear. Diesel stayed strong, Middle East logistics stayed uncertain, and refiners remained disciplined. The market may be less frantic, but it is not yet comfortable.
RECENT HEADLINES
U.S. REFINERIES
US Crude Refiners Are Pushing Run Rates to Maximum Levels
US oil refiners are running their plants harder than usual, with some even putting off maintenance, as strong profits and steady demand for fuels tempt the processors to run plants near maximum capacity.
The industry has had one of its lightest maintenance seasons in years. From January through May, refiners shut down an average of 470,000 barrels a day in processing capacity. That compares with 700,000 during the same period last year and 900,000 in 2024, according to consultancy Energy Aspects.
The trend looks set to continue.
One case in point: Motiva Enterprises LLC has delayed a major maintenance project at its Port Arthur refinery on the Texas Gulf Coast by about a year to take advantage of strong product margins. That includes work at its biggest crude unit, with the delay pushing the turnaround into the fall of 2027, people familiar with the operations have said.
“So far, there’s not a lot of maintenance in the books for second half of the year,” said Raul Calzada, a refining analyst at Energy Aspects’s Houston office. “Demand for refined products is going to be high, so the market needs refiners to run hard the rest of the year.”
There is a tradeoff. The longer refiners postpone maintenance while operating near full capacity, the greater the risk of unexpected breakdowns that can force units offline, Calzada said. Continue Reading Here
Chevron Eyes Egyptian Export Route for Cyprus Gas
Chevron and Egypt are seeking to accelerate agreements needed to connect Cyprus’ Aphrodite gas field to Egyptian infrastructure, as Cairo looks to strengthen its role as an Eastern Mediterranean gas hub.
Egyptian Petroleum Minister Karim Badawi held talks with Chevron executive Javier La Rosa this week, with discussions focused on finalizing the technical, financial and commercial frameworks required to move the project forward. The two sides also discussed expanding Chevron’s gas exploration activities in Egypt’s Mediterranean waters.
The talks represent the latest effort to advance Aphrodite. Egypt said in March that technical and legal teams were already preparing key agreements for linking the field to Egyptian infrastructure, potentially allowing its gas to be processed and re-exported to international markets.
Discovered in 2011, Aphrodite lies in Cyprus’ offshore Block 12, around 170 kilometers southeast of the island. Chevron operates the field with a 35% interest alongside Shell and NewMed Energy. Continue Reading Here
Phillips 66 Is Minting Money on $102 Diesel Margins. How Long Can It Last?
Phillips 66 (NYSE:PSX) closed Friday at $272.99, up 116.03% year-to-date, after a second quarter that generated $52.04 billion in revenue and $9.41 in adjusted EPS against a $8.0855 consensus.
Refining drove the quarter: worldwide realized margins jumped to $24.08 per barrel from $10.11 per barrel the prior quarter. This was the strongest quarterly result since 2022.
The key question is whether investors are paying for a temporary war premium that will fade or a permanent tightening that will persist. Diesel cracks recently ran roughly five times the typical teens-to-low-twenties range because Russian export flows collapsed, Persian Gulf shipments fell, and Ukrainian drone strikes hobbled Russian throughput. None of that is a run rate. Continue Reading Here
‘Dammit, something has to happen’: White House preparing plan for 90-day diesel exports ban
The Trump administration is preparing a plan to ban exports of diesel for 90 days, despite splits inside the administration and with the oil industry, in a bid to bring down energy prices weighing on Republicans leading into the midterms, five people familiar with the discussions said Wednesday.
A ban, the legal process of which is still being worked out, has been opposed by U.S. fuel producers who have warned that any short-term benefit would be outweighed by higher fuel prices in the future. Any halt to shipments would be the first restriction on U.S. energy exports since the Obama administration lifted a decades-old ban on oil exports in 2015. Continue Reading Here
NON U.S. REFINERIES
Ukrainian Drone Swarm Strikes Key Russian Oil Refinery in Samara
Dozens of Ukrainian drones targeted industrial facilities in Russia’s Samara Oblast overnight on Tuesday, damaging civilian infrastructure and reportedly setting fire to a major Rosneft oil refinery.
Samara Governor Vyacheslav Fedorishchev said the drones targeted industrial enterprises and that private homes and vehicles were also damaged. He did not report casualties.
Astra, citing eyewitness footage, identified the target in Samara as the Kuibyshev oil refinery, one of the region’s largest. A major fire broke out at the facility following the attack. Continue Reading Here
Major Russian LUKOIL Refinery Targeted in Second Drone Attack Since August
The LUKOIL-Permnefteorgsintez (PNOS) oil refinery, one of Russia’s largest processing facilities, was targeted in a new drone attack, the independent Russian outlet ASTRA reported on September 25, citing OSINT analysis.
Perm regional Governor Dmitry Makhonin confirmed the strike on the region, noting that first responders had been deployed, according to ASTRA. Continue Reading Here
Shell Completes $840 Million Gulf Oil Asset Sale
Shell has completed the sale of its interests in two U.S. Gulf of Mexico assets to Talos Energy and Ridgewood Energy, collecting approximately $840 million in cash at closing.
The transaction includes Shell’s former 50% non-operated interest in BP-operated Na Kika and its 100% interest in the Coulomb tieback. Talos acquired a 25% stake in Na Kika and a 50% interest and operatorship in Coulomb, while Ridgewood acquired the remaining interests divested by Shell.
The deal was originally announced in June with total consideration of $1.7 billion before adjustments and contingent payments. Talos ultimately paid $420 million for its share, including a previously paid $42.5-million deposit.
The acquired Talos interests produced around 16,000 barrels of oil equivalent per day in the first quarter of 2026, approximately 77% of which was oil. Talos estimates the interests contain roughly 23 million boe of proved reserves and another 10 million boe of probable reserves. Continue Reading Here
THE CRUDE SIDE
Japan Oil Refiners Expect to Secure Enough Supply to Replace Middle East Crude for Summer
Japanese oil refiners will be able to secure sufficient substitute crude and petroleum products to replace Middle Eastern supplies through the summer, the head of an industry association said on Wednesday.
Shunichi Kito, president of the Petroleum Association of Japan, said that U.S. crude is becoming the main substitute while efforts continue to procure crude from Saudi Arabia and the UAE via routes that bypass the Strait o Some Japanese companies are sourcing crude from Latin America, including Mexico, Ecuador and Venezuela, as well as from Alaska and Russia’s Sakhalin-2.
“We are responding through a combination of drawing down national reserves and sourcing alternative supplies,” Kito said.
“We expect no procurement problems during the peak summer demand season.”f Hormuz. Continue Reading Here
Tanker Rates Smash $1 Million a Day as Oil Shipping Crisis Deepens
The daily rate for commissioning a tanker topped $1 million for the first time in history amid a tightening supply of vessels to carry crude oil and fuels whose owners are willing to dare the Strait of Hormuz. The squeeze is adding extra costs to the price of oil for physical delivery, just as tankers become a cybersecurity target.
Bloomberg reported record-high tanker rates earlier this week, noting that tankers commissioned to pick up crude from inside the Persian Gulf fetched as much as $1.035 per day, based on data from the Baltic Exchange. Rates for tankers outside the Gulf have also gone up substantially, the publication noted, citing a daily rate of $644,000 for a tanker carrying crude from the Gulf of Oman—which is outside Hormuz—to China. Continue Reading Here
US Gasoline, Distillate Inventories Continue to Fall as Crude Stocks Hold
The American Petroleum Institute (API) estimated that crude oil inventories in the United States rose by 1.786 million barrels in the week ending September 18. In the week prior, US crude oil inventories grew by a substantial 7.14 million barrels.
Commercial crude oil inventories excluding the SPR have lost 39 million barrels over the last 23 weeks, but US crude inventories are up nearly 12 million for the year, according to API data, kept in check by draws from the SPR. Continue Reading Here
Surprising Fun Facts About the Oil Industry
- Early oil wells were sometimes stored in open pits before tanks were common. – Operators would literally let crude collect in dug-out earth pits, which caused huge losses from seepage, evaporation, fire, and contamination.
- Before pipelines, teamsters sometimes made more money than oil producers. – In early oil regions, moving crude by wagon was so expensive that transportation could eat up much of the barrel’s value.
- Some early refiners dumped gasoline because kerosene was the prize. – Before the automobile age, gasoline was unstable, dangerous, and not nearly as valuable as lamp fuel.
- Standard Oil’s real power was not just owning oil. It was controlling logistics. – Storage, rail rebates, pipelines, refining, barrels, export channels, and distribution mattered as much as crude supply.
- The first big oil fights were often about transportation, not production. – Whoever controlled rail access, pipeline routes, tank cars, and terminals often controlled the economics of the whole region.
- Some crude oils are valuable because they are easy to refine, not because they are rare. – Light, sweet crude can be worth more because it produces cleaner, higher-value products with less processing.
- Heavy crude can be worth far less even when there is plenty of demand for oil. – If it needs complex refining, dilution, heating, or upgrading, the logistics and processing burden can drag down its value.
- A refinery’s crude diet is like a recipe. – Refineries are built around certain types of crude. A cheap crude is not always useful if the refinery is not designed to handle it.
- Oil prices can move even when physical barrels do not. – Paper trading, hedging, futures, freight, storage economics, and refinery margins can move market sentiment before physical supply changes hands.
- The oil industry has always been a margin business, not just a volume business. – The winners are often not the ones with the most barrels, but the ones who manage timing, logistics, quality, blending, storage, and customer access best.
SUGGESTED READING
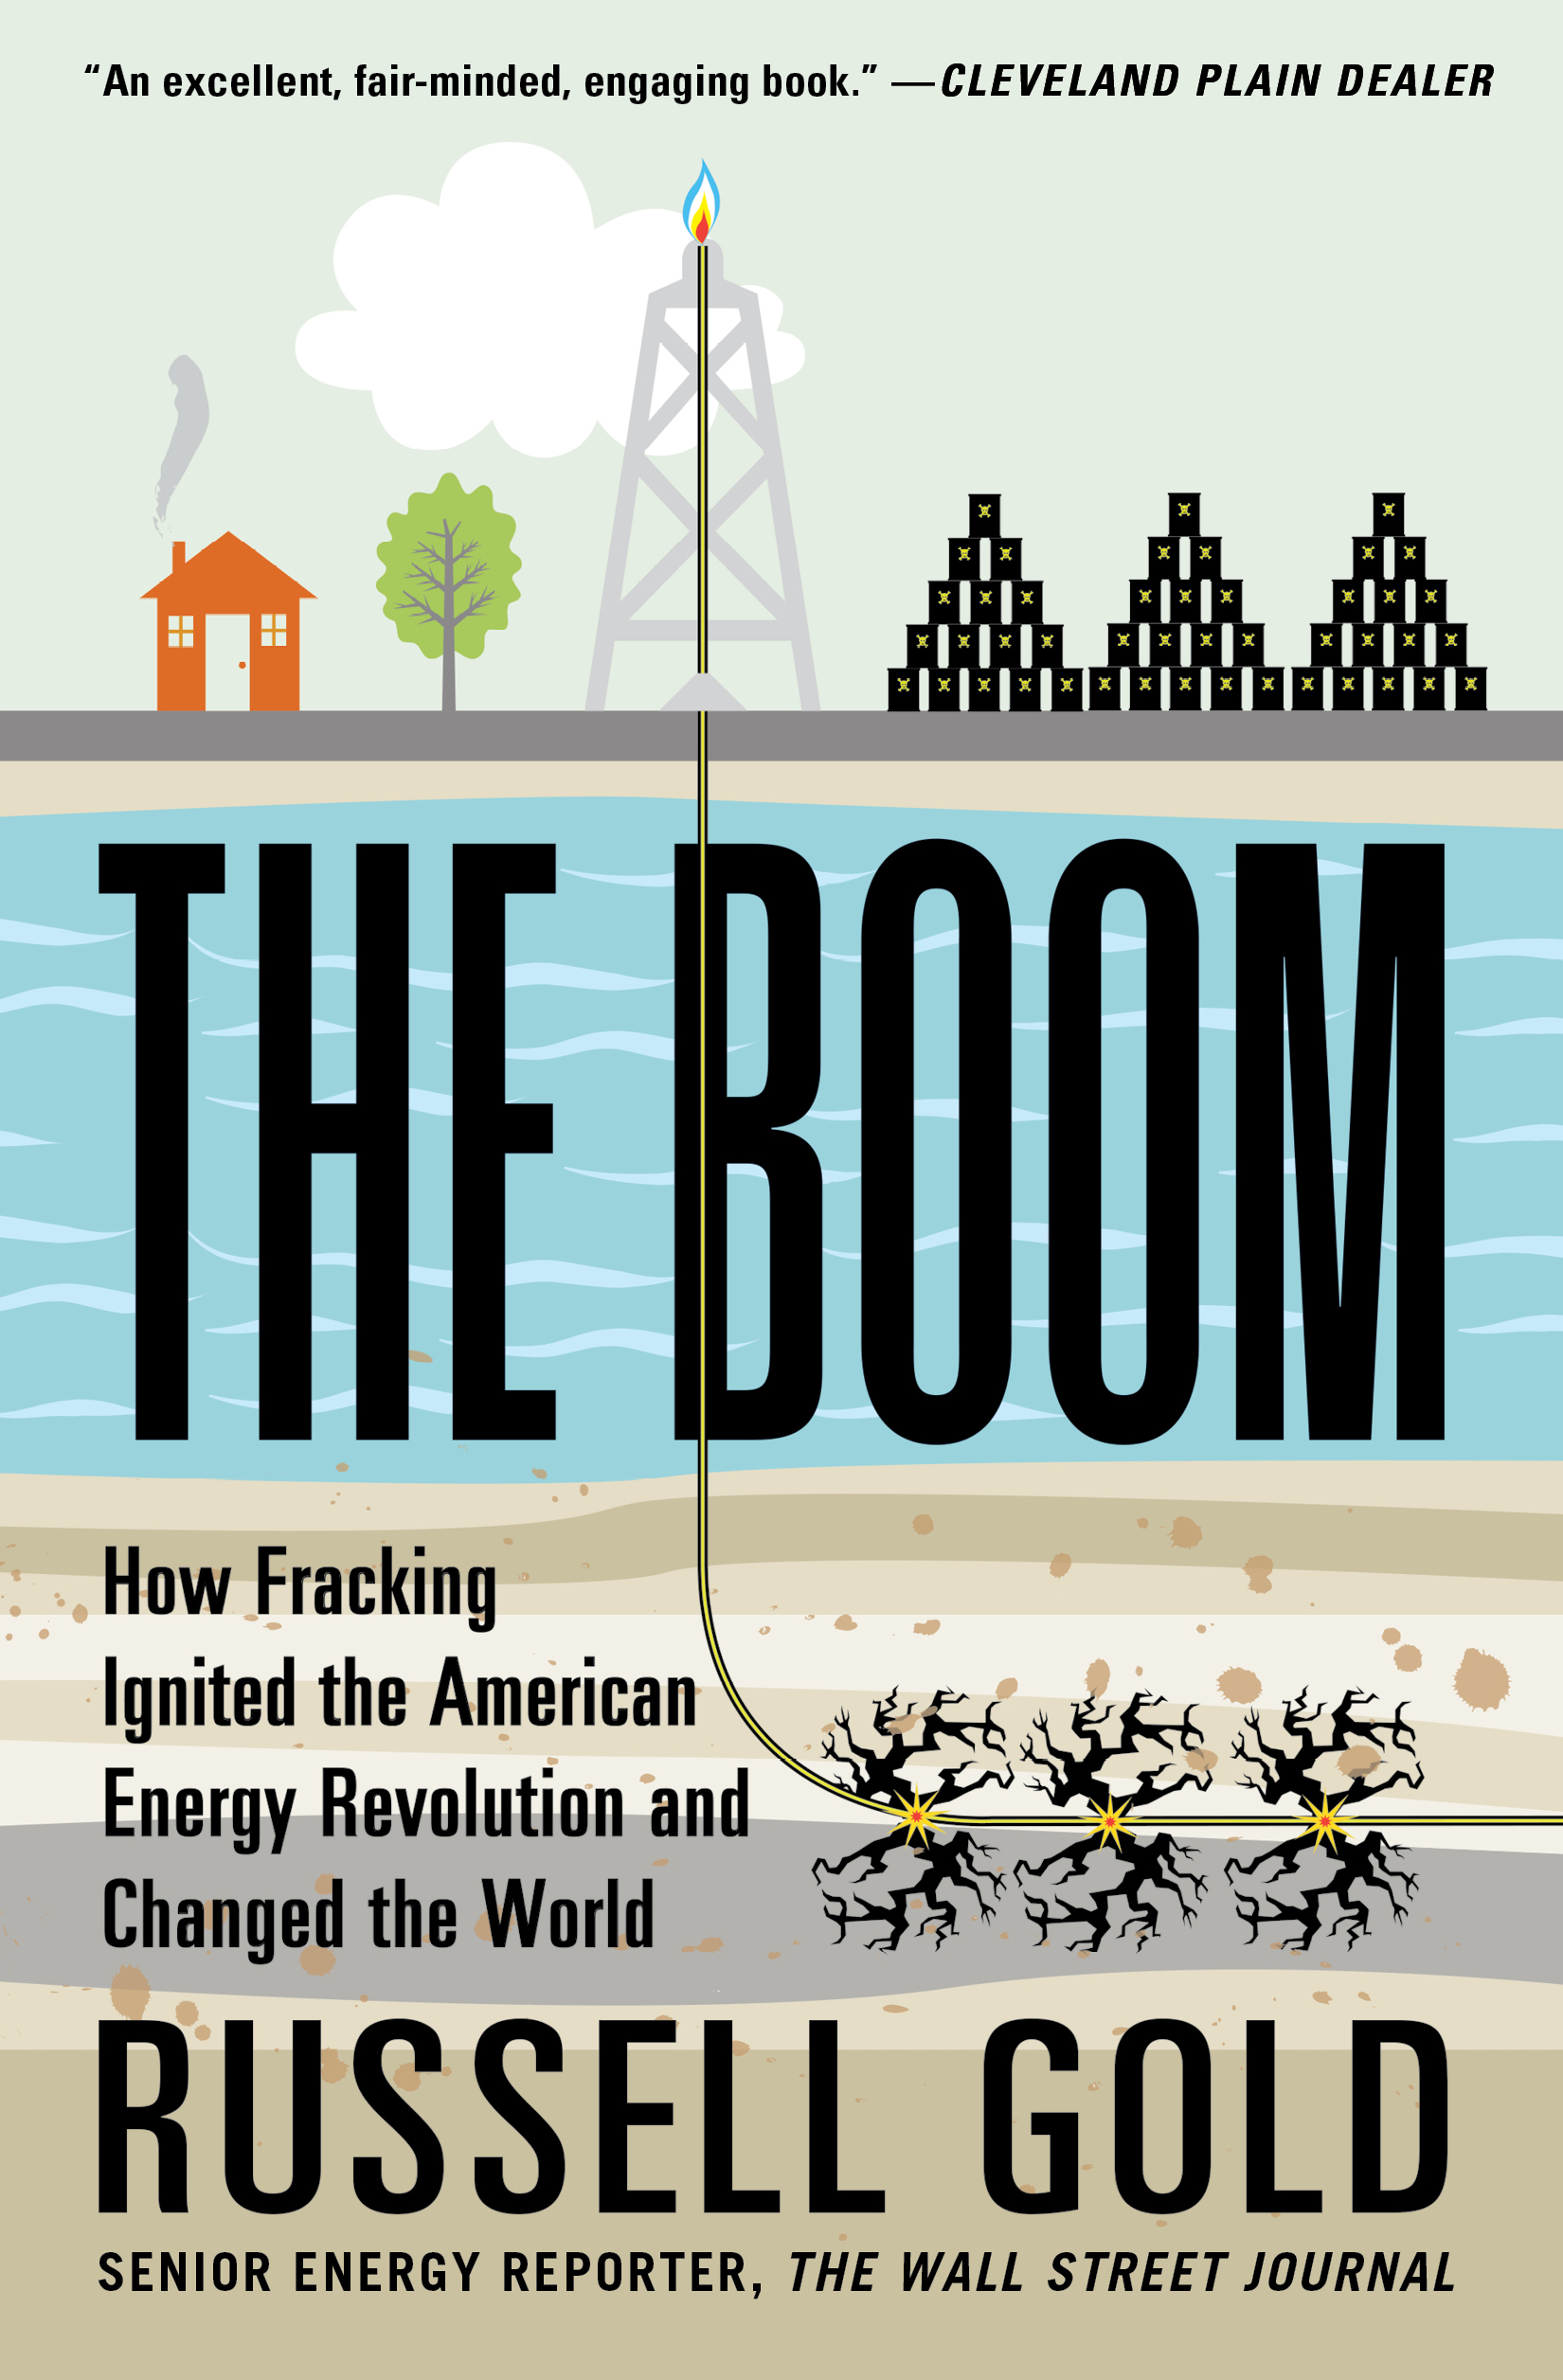
The Boom: How Fracking Ignited the American Energy Revolution and Changed the World Book by Russell Gold
The Boom tells the story of America’s shale revolution in a way that is easy to read and full of real-world energy drama. Russell Gold follows the people, technology, money, and risk that helped unlock a new era of domestic oil and gas production. It is a strong pick for anyone who enjoys big industry shifts, oilfield ambition, and the story of how innovation reshaped the modern energy landscape.
WE’VE COME A LONG WAY!
Thank you for joining us in this edition of the Beyond the Barrel Newsletter. Feel free to reach out to the Signal Fluid Solutions team for any inquiries or discussions.